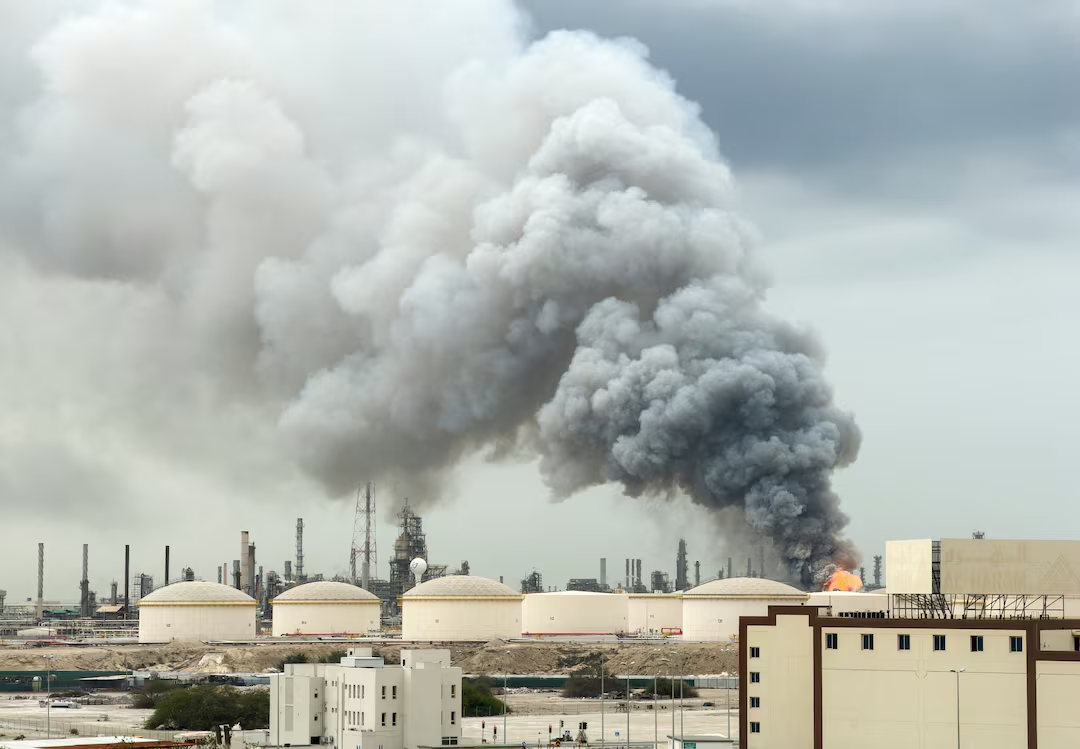
Amid the war on Iran, Gulf states and companies find themselves facing a massive repair bill one no less consequential than the immediate losses in exports following Tehran’s targeting of oil and gas facilities across the region.
Preliminary estimates by the U.S.-based firm Rystad Energy suggest that the cost of rehabilitating the Gulf’s energy infrastructure could exceed $25 billion. The figure is likely to rise, as it accounts for extensive damage to LNG liquefaction lines, refineries, storage facilities, ports, and even some power stations.
Yet the central question is not merely the size of the bill, but where the money will go, who will pay it, and whether it will reshape the Gulf’s investment landscape.
Where Does the Bill Lie?
1. Liquefied Natural Gas: Ras Laffan, Qatar as a Case Study
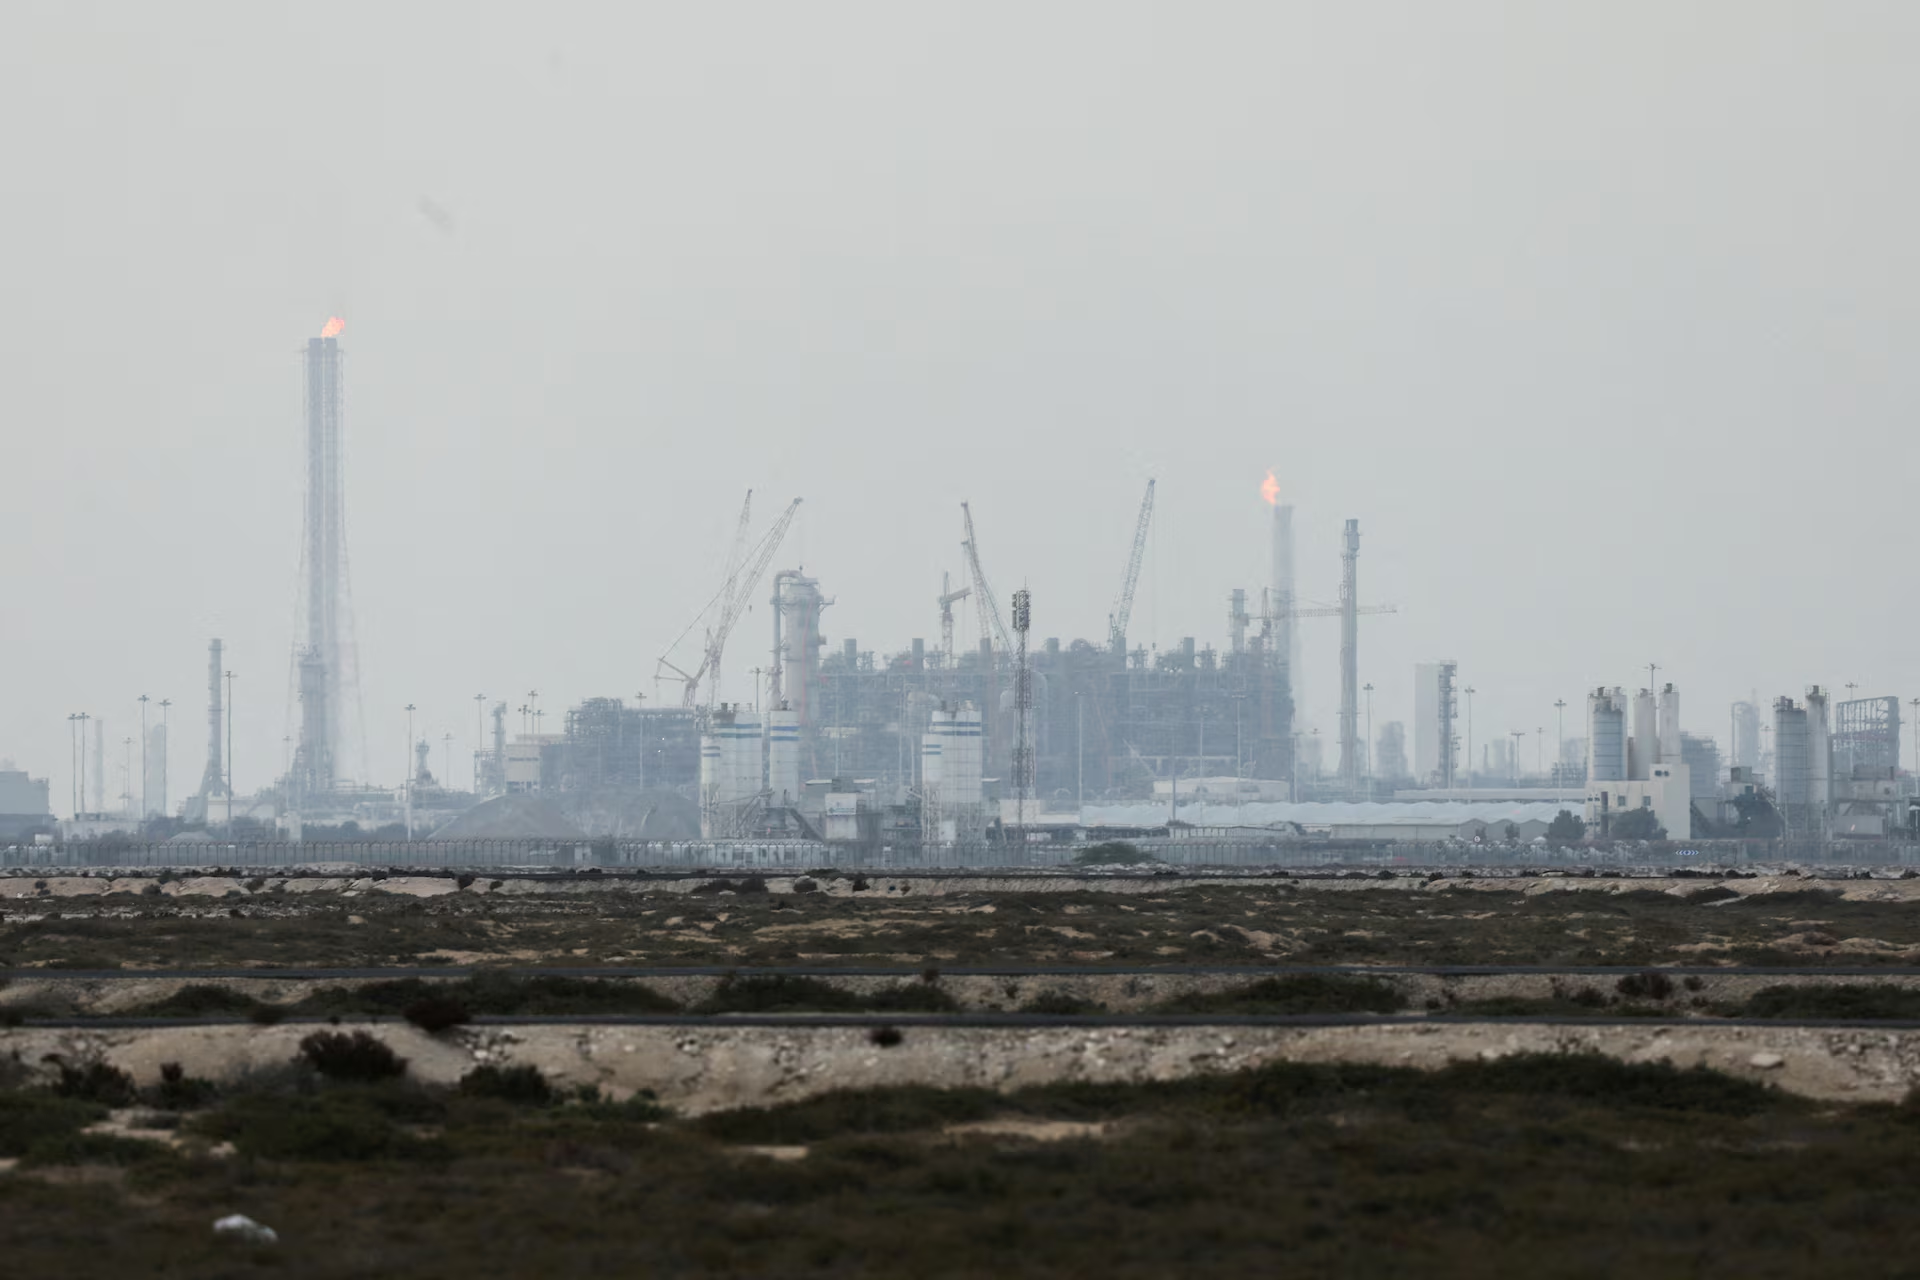
The largest component of the repair bill lies in the liquefied natural gas (LNG) sector. For instance, an Iranian strike on Ras Laffan Industrial City in Qatar destroyed two out of 14 liquefaction trains, as well as a gas-to-liquids (GTL) facility.
The result was a shutdown of 17% of Qatar’s gas export capacity equivalent to 12.8 million tons annually. Repairs and reconstruction are expected to take between three and five years, due to global shortages in the supply of large gas turbines.
The CEO of QatarEnergy estimated annual revenue losses at around $20 billion, confirming that the company would declare force majeure on long-term contracts with Italy, Belgium, South Korea, and China.
It is important to distinguish between market losses (i.e., declining market share) and actual repair costs. The former reflects lost revenues, while the latter concerns rebuilding damaged units.
2. Refineries: Bahrain’s Sitra and Saudi Arabia’s Ras Tanura
The second layer of costs relates to refineries. Iranian drones targeted Bahrain’s Sitra refinery (BAPCO) twice in March just two years after the completion of a $7 billion modernization project.
The attacks damaged new distillation units and a fuel storage tank, forcing the company to bring back international contractors under uncertain wartime security conditions.
In Saudi Arabia, the Ras Tanura refinery (550,000 barrels per day) was also hit. However, the presence of local maintenance teams enabled a relatively swift restart.
These incidents underscore that repair costs depend not only on the scale of damage, but also on each country’s ability to rapidly mobilize contractors and equipment.
3. Storage, Ports, and Supporting Infrastructure
The bill also includes damage to storage facilities, export terminals, and supporting power stations in the UAE, Kuwait, and Iraq.
According to IIR data, attacks led to the disruption of approximately 1.9 million barrels per day of refining capacity across the Gulf, following outages in Kuwait, Bahrain, and Iraq, as well as maintenance-related shutdowns in Ras Tanura.
Additionally, attacks on gas facilities in the UAE and Kuwait caused fires and production cuts. However, sources indicate that the physical damage there is less severe than in Ras Laffan and Sitra, meaning repairs could be completed within months.
Sectoral Breakdown of Costs
According to Rystad Energy, 49% of repair costs will go to engineering and construction, 39% to equipment and materials, while logistics and operations will each account for no more than 6%.
In other words, the bulk of spending will be directed toward rebuilding core infrastructure and commissioning new facilities, while comparatively smaller amounts will be spent on transportation and project management.
This breakdown highlights why engineering is the most expensive segment particularly in LNG projects, which require large turbines and specialized expertise.
It also explains why some assets can be repaired within months (such as refineries with local maintenance teams), while others like complex LNG liquefaction units may take years.
Who Will Actually Pay?
1. Governments and National Oil Companies
Most oil and gas facilities in the Gulf are state-owned or operated by national companies such as QatarEnergy, ADNOC, and Saudi Aramco.
Given that most insurance policies exclude acts of war, governments and national companies will likely bear a significant share of repair costs through their budgets or sovereign reserves.
A report by Fitch Ratings notes that most property damage and business interruption policies exclude war-related events. As a result, claims related to energy infrastructure damage are expected to be limited.
In simpler terms, the burden on global insurers will not primarily stem from property insurance, but rather from sectors such as marine and aviation. Fixed infrastructure losses will largely go uncompensated, forcing governments to directly finance repairs potentially straining budgets and delaying other projects.
2. Insurance Companies and Coverage Limits
Marine protection and indemnity (P&I) clubs including Gard, Skuld, NorthStandard, London P&I, and the American Club announced the cancellation of war risk coverage in Iranian and Gulf waters starting March 5.
Japan’s MS&AD group also suspended issuing war risk policies in the region. Moreover, transit through the Strait of Hormuz now requires mandatory war insurance through Lloyd’s of London.
Fitch reports that marine insurance premiums have surged to 20 times normal levels. Compensation for a single incident can reach several hundred million dollars, with a cap of $500 million per event.
These figures make clear that marine insurance covers ships and cargo not land-based facilities. Coverage for fixed infrastructure against war is virtually nonexistent.
3. External Financing and Contractor Challenges
To mitigate shipping risks, the U.S. International Development Finance Corporation (DFC) launched a $20 billion maritime reinsurance program, led by Chubb, to cover vessel and cargo losses transiting Hormuz.
However, the program focuses on trade flows not on rebuilding refineries or gas plants leaving Gulf states to shoulder most of the burden.
An additional challenge lies not just in financing, but in the availability of contractors and equipment. Security concerns have prompted some international engineering firms to withdraw, while the production of large gas turbines is concentrated among a limited number of suppliers, potentially extending delivery timelines.
Will the Gulf’s Investment Map Change?
1. Delayed Expansion and Reprioritization
The war has already reshaped Gulf priorities. Before the crisis, Qatar, Saudi Arabia, and the UAE had announced plans to expand LNG and petrochemical capacity.
However, the repair bill may delay some expansion projects, redirecting spending toward reconstruction and rehabilitation.
Rystad Energy expects repair spending to take precedence over new growth projects, with engineering service firms shifting focus from developing new fields to maintaining damaged assets.
Meanwhile, global oilfield service companies caution that higher profits driven by rising prices will not necessarily translate into increased investment, as firms typically require five to seven years of price stability before approving new projects.
2. Fortification and Logistical Resilience
Beyond repairs, the war is pushing governments to invest more in fortification and resilience. The targeting of export terminals and refineries has exposed vulnerabilities in key chokepoints such as the Strait of Hormuz and ports in Bahrain and Qatar.
Countries are expected to allocate more resources toward air defense systems around critical infrastructure, building alternative storage facilities, and developing pipelines that bypass high-risk areas.
There may also be greater emphasis on energy efficiency and supply chain redesign to enhance resilience during disruptions. These investments are as crucial as reconstruction, as they reduce the likelihood of similar losses in the future.
3. Revisiting Long-Term Economic Visions
Finally, there is a deeper dimension tied to long-term economic visions. Countries such as Saudi Arabia, Qatar, and the UAE have spent years pursuing diversification strategies away from oil.
However, the high cost of war may strain the resources available to fund such initiatives particularly in countries with more limited financial reserves, such as Bahrain.
Fitch’s decision to place Qatar on negative watch due to damage at Ras Laffan suggests that physical losses can translate into sovereign credit risks, potentially affecting borrowing costs for long-term development projects.
While higher oil prices provide additional revenues, war tends to make investors more cautious, forcing governments to allocate a larger share of income toward security and repairs rather than launching new ventures.